Nothing else existed.
Every processing company promises to work inside your LOS. The promise is for your comfort, not your loan's success. SouthCoast Processing built the platform the job actually needs.
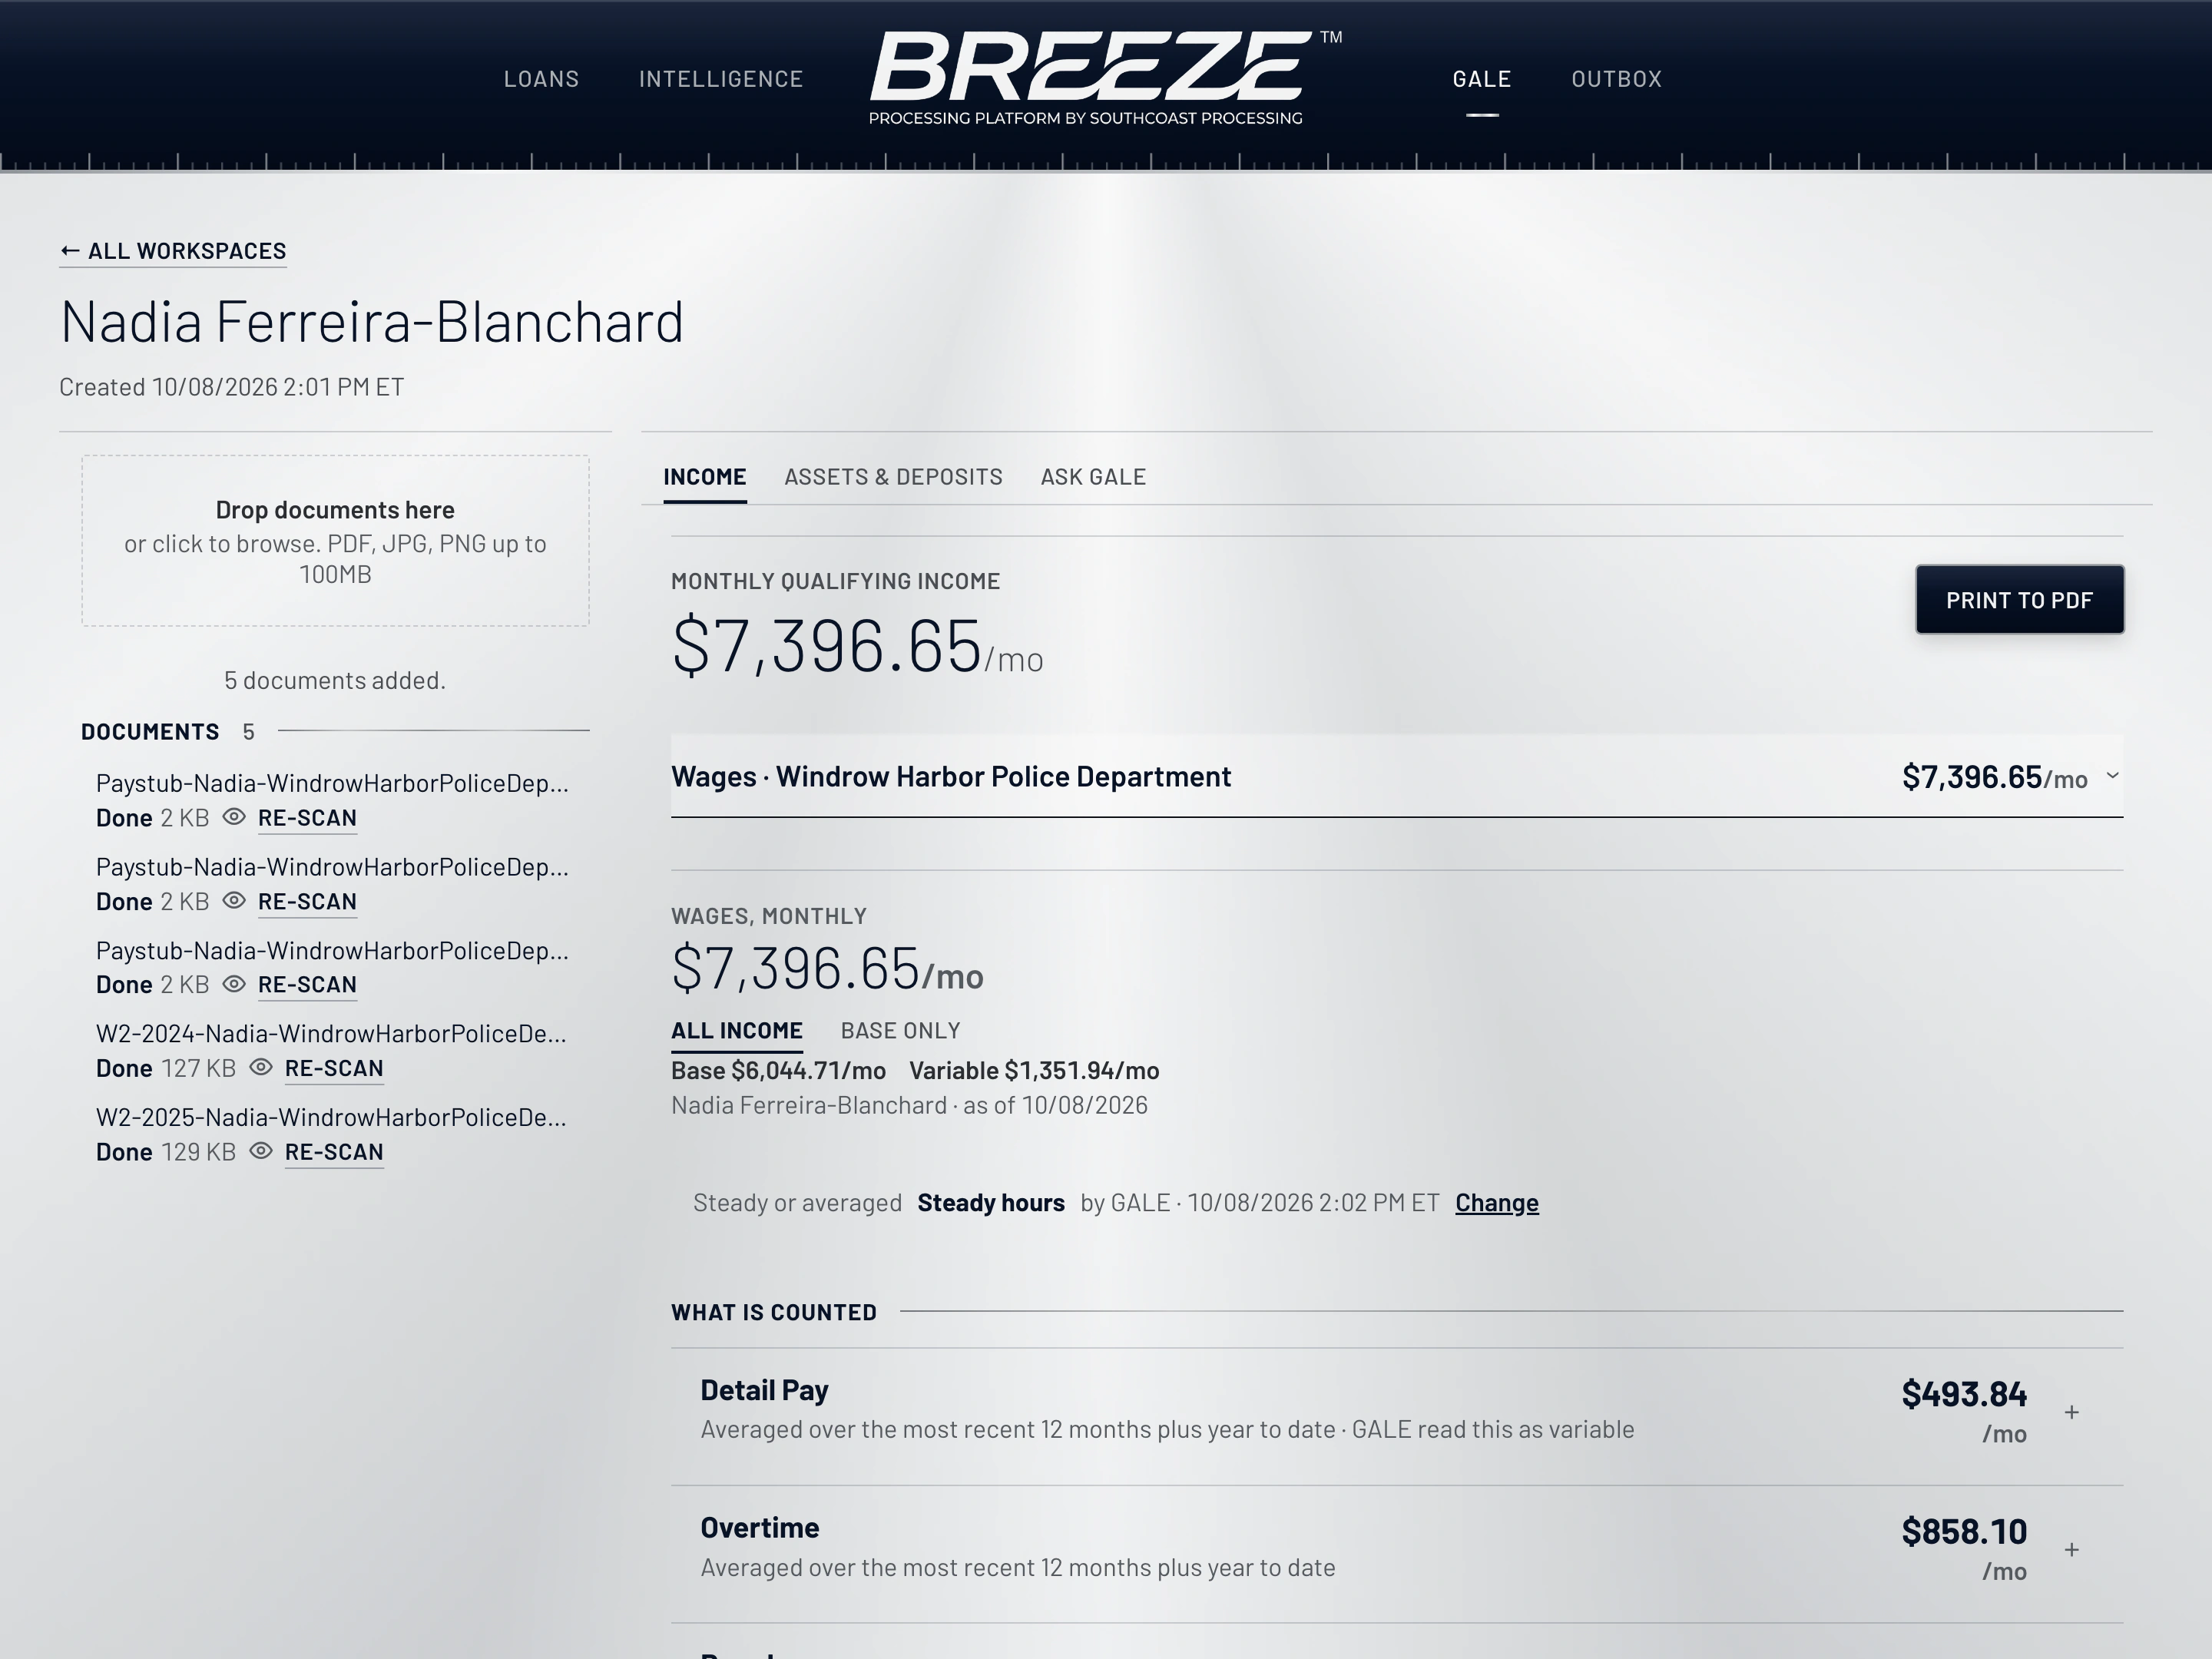
Five documents in.
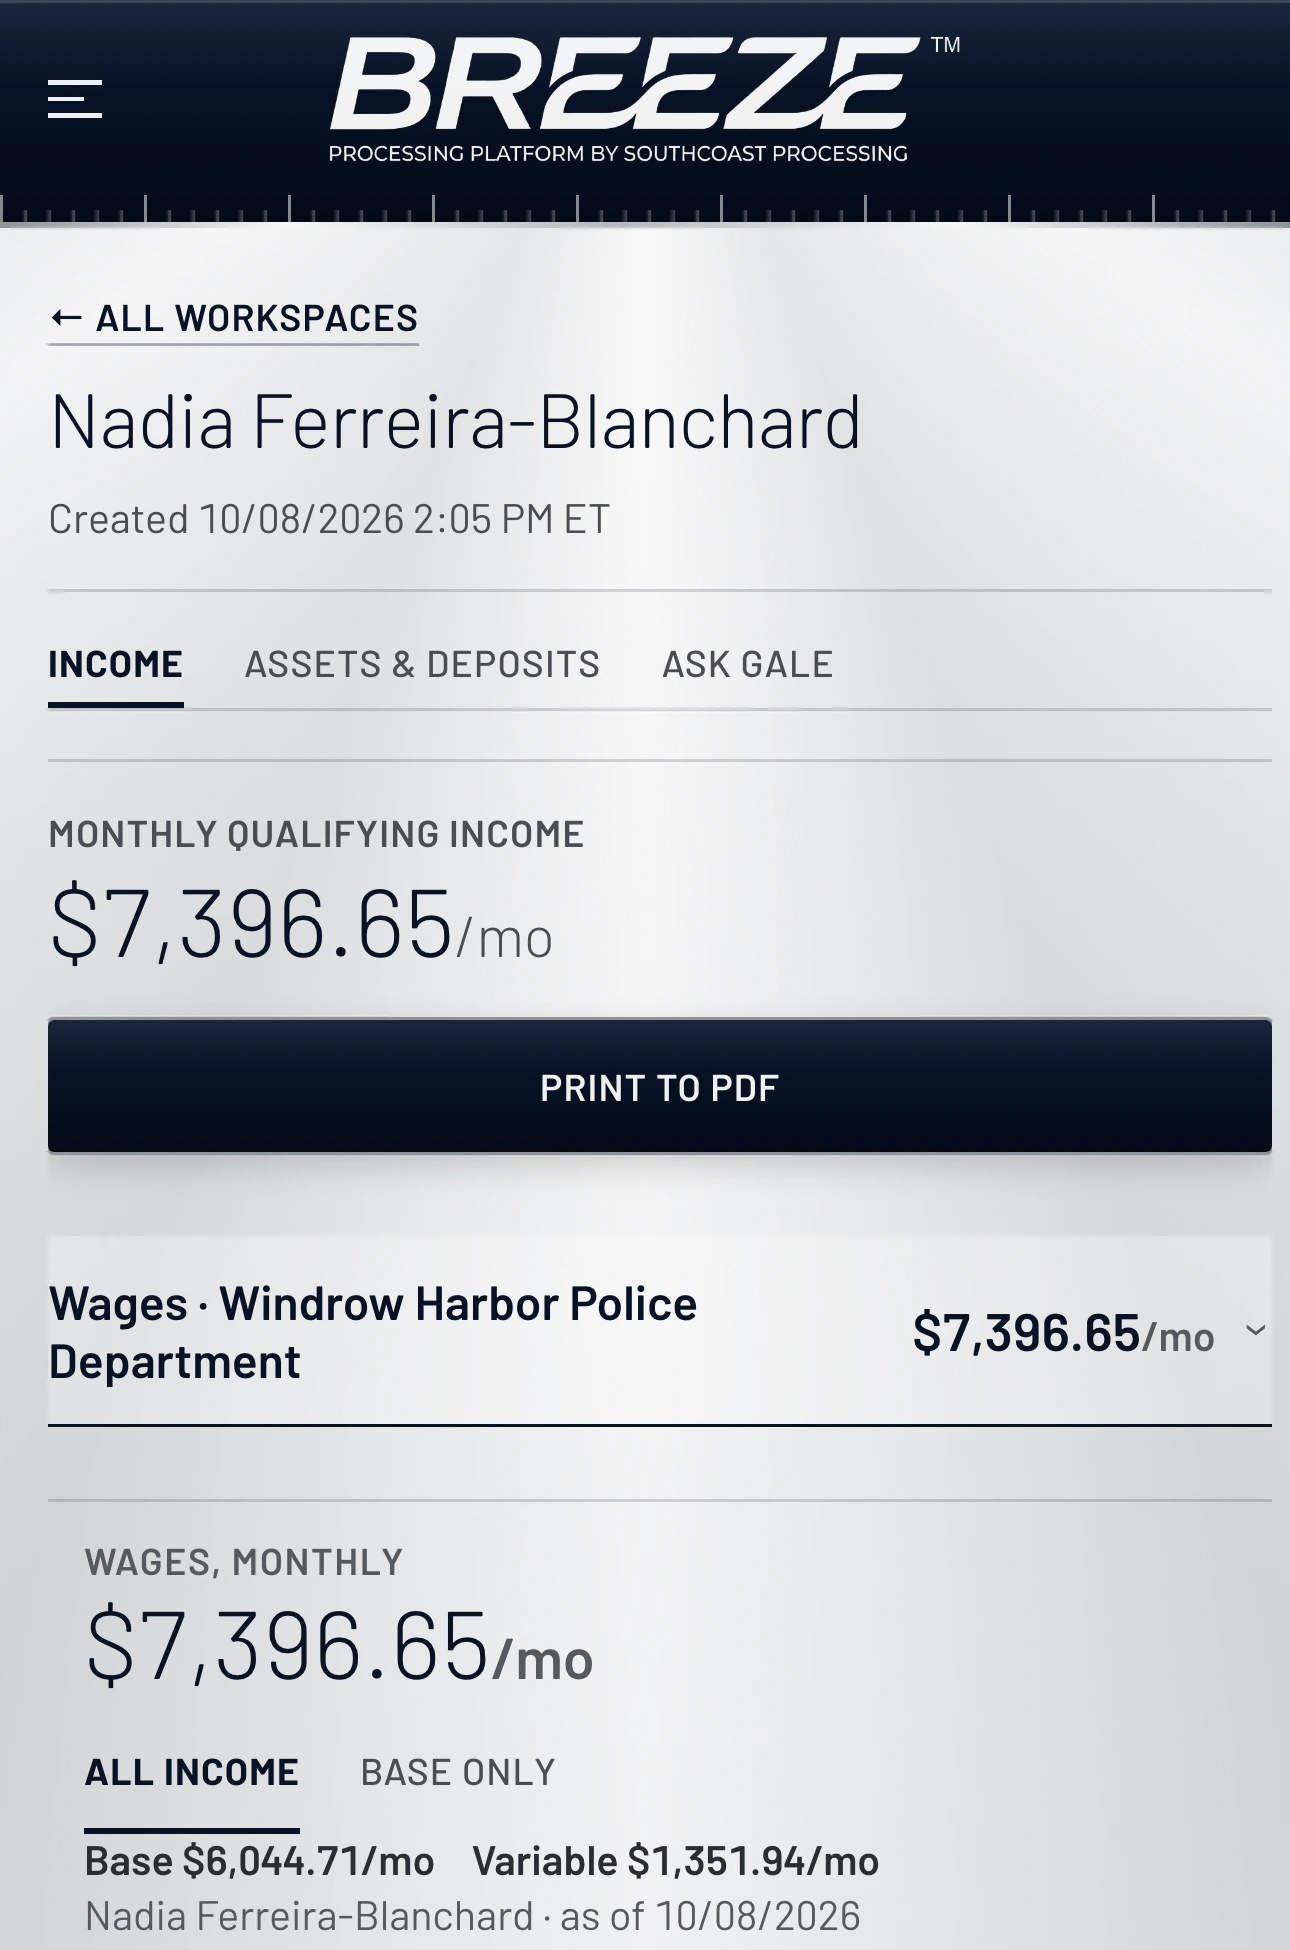
Drop in the pay stubs and the W-2s. GALE (Guideline Analysis & Loan Evaluation) reads them, separates base from overtime from detail pay, and hands back the qualifying income with its work shown.


Ask it anything.
Ask SCP Mortgage AI a guideline question the way you would ask an underwriter. It answers from the guidelines themselves, knows which loan you're talking about, and cites and links the section that applies. It's written to think like a processor and focused on one task: how do we get this loan to "yes"?


It checks the lender's system every hour.
After initial approval, Loan Intelligence checks the lender's system every hour, pulls in the conditions and the lender's loan file, compares them against BREEZE, and makes sure your loan is always in sync. Every condition gets an AI review of whether the underwriter is correct. If a condition is unnecessary or overreaching, an escalation is automatically prepared for your processor.

Saturday. The sideline. The buyer's agent texts.
"Any update on the appraisal?" You open BREEZE. Ordered on 10/1. Paid and accepted on 10/2. Scheduled for 10/5. You answer from the sideline with all three. Nobody waits for Monday.

Everything, as it happens.
This is why the LOS was never the answer. Open any loan in BREEZE and it's all there, live.
- The status of every third-party service, in real time. Title, insurance, appraisal, payoffs, verifications.
- A time-stamped log of every step. Who on the team did what on your loan, and when.
- Every phone call on the loan, as a transcript or the recording. To the borrower, the agent, the title company, the employer verifying a job.
- The full history of every text message sent on the loan.
- Every file on the loan the moment it lands, with a preview.
- GALE, SCP Mortgage AI, and Loan Intelligence, on every loan.
On your phone, because your borrowers don't stop asking questions at five.
Your LOS still gets everything.
Your LOS still matters, and BREEZE was built knowing that. If you're on ARIVE or LendingPad, every key piece of loan information and every document syncs back to your LOS when the loan closes, so compliance is a breeze. On any other LOS, one export does it.
We're particular about who we work with.
Tell us how you run your business. If it's a fit, you'll know quickly. If it isn't, we'll say so.